Overdue invoices are a common challenge for businesses that sell on credit or provide services before receiving payment. When customers delay settlement, cash flow can come under pressure, operational plans may be disrupted and the risk of bad debt can increase. However, an overdue invoice does not automatically mean that the amount will become unrecoverable.
Successful debt recovery is usually the result of a structured process rather than a single phone call or payment reminder. It involves identifying overdue accounts early, confirming that balances are accurate, understanding why payment has been delayed, engaging customers professionally and taking proportionate action when commitments are not met.
The objective is to recover legitimate outstanding amounts while maintaining accurate records, protecting customer relationships and ensuring that every recovery action is properly documented.
The Journey from Overdue Invoice to Recovery
An effective recovery process moves an account through clear stages. The level of intervention should reflect the age and value of the debt, the customer’s payment history, the reason for delay and the quality of the supporting documentation. Acting early can often resolve an account before more intensive recovery measures become necessary.
Six Practical Steps to Improve Debt Recovery
1. Identify and Prioritise Overdue Accounts
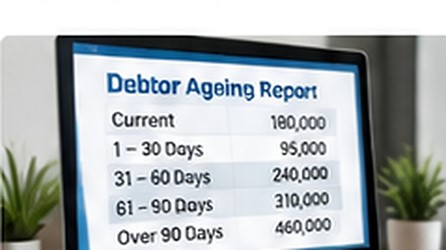
The first step is to establish which invoices are overdue and determine which accounts require attention first. An up-to-date debtor ageing report helps show the value of outstanding balances and how long each invoice has remained unpaid. It can also highlight customers with repeated late-payment patterns or balances that are increasing over time.
Prioritisation should consider more than the age of an invoice. The amount outstanding, customer history, agreed credit terms, previous payment commitments and available recovery information can all help determine the appropriate follow-up.
Practical action: Review debtor ageing regularly, flag high-value and long-outstanding accounts, and assign responsibility for each account.
2. Verify the Debt Before Making a Recovery Demand
Before contacting a customer about an overdue balance, confirm that the amount being pursued is accurate and supported by the relevant records. Check the invoice, purchase order or contract, delivery or service evidence, payment history, credit notes and any previous correspondence.
This verification helps identify payments that have not been allocated, invoices that were sent to the wrong contact, duplicate entries or legitimate billing disputes. Pursuing an incorrect balance can undermine customer confidence and delay recovery.
Practical action: Reconcile the account and ensure that the supporting documents are complete before escalating the matter.
3. Engage the Customer Early and Professionally
Early engagement gives the business an opportunity to understand why an invoice has not been paid. A courteous call or written reminder can establish whether the customer received the invoice, whether it has been approved for payment and whether any documentation or clarification is needed.
Keep the conversation factual and focused on resolution. Confirm the invoice reference, outstanding amount and due date, ask for the reason for delay, and establish a realistic date for payment. Record the contact person, discussion outcome and agreed next action.
Practical action: Use a consistent follow-up schedule and maintain a clear record of every customer interaction and payment commitment.
4. Resolve Payment Barriers and Agree on a Clear Solution
Not every delayed payment is caused by unwillingness to pay. Some accounts may be affected by invoice discrepancies, internal approval delays, missing documents or temporary cash-flow constraints. Understanding the reason for non-payment helps determine the most appropriate response.
Where a genuine dispute exists, investigate it promptly and communicate the findings. Where the customer acknowledges the debt but cannot pay the full amount immediately, an authorised payment arrangement or restructuring plan may provide a practical route to settlement. The amount, dates and conditions should be documented and monitored.
Practical action: Agree on specific payment dates and amounts in writing, obtain the required internal approval and follow up each commitment.
5. Escalate Accounts When Routine Follow-Up Is Not Enough
If repeated reminders do not produce payment, or a customer consistently fails to honour agreed commitments, the account may require a more formal recovery approach. Escalation should be based on the account history, supporting evidence, risk and applicable contractual requirements.
Depending on the circumstances, next steps may include senior-level engagement, a formal demand letter, field collections, skip or asset tracing where appropriate, or legal recovery support. These actions should be proportionate, properly authorised and carried out in accordance with applicable laws and professional standards.
Practical action: Apply a documented escalation process, preserve the account history and refer complex or late-stage cases for appropriate specialist review.
6. Confirm Payment, Reconcile the Account and Close the Recovery
Recovery does not end when a customer says that payment has been made. Confirm receipt through the relevant bank or payment records, allocate the amount to the correct customer account and invoice, and update the outstanding balance. If payment is partial, ensure that the remaining amount is clearly recorded and followed up.
Once the balance has been settled, issue or update the relevant statement or receipt, close the recovery activity and retain the supporting records. Accurate closure prevents settled accounts from being pursued again and supports reliable management reporting.
Practical action: Reconcile every receipt, update the account promptly and record the final recovery outcome.
When Should an Overdue Account Be Escalated?
Escalation becomes important when ordinary follow-up is no longer producing progress. Warning signs may include repeated broken payment promises, prolonged non-response, rapidly increasing balances, recurring unsupported disputes or indications that the customer may be difficult to locate. No single sign should automatically determine the outcome; the account should be assessed using the available facts and supporting records.
Before moving to a more formal recovery stage, confirm the amount owed, review the contractual position, document previous engagement and check whether any genuine dispute remains unresolved. The selected action should be proportionate to the circumstances and consistent with the organisation’s policies and applicable legal requirements.
Measuring Debt Recovery Performance
A structured recovery process should be supported by clear reporting. Useful indicators help management understand not only how much has been collected, but also where delays occur and which recovery activities are producing results.
- Recovery rate: the proportion of targeted overdue balances collected during a defined period.
- Debtor ageing: the value of outstanding invoices grouped by the length of time they have remained unpaid.
- Days Sales Outstanding (DSO): the average number of days taken to collect payment after a credit sale.
- Promise-to-pay fulfilment: the proportion of recorded payment commitments honoured by customers.
- Dispute resolution time: the time taken to investigate and resolve invoice or account discrepancies.
- Unallocated cash: payments received but not yet matched to the appropriate customer account or invoice.
Regular reporting allows management to identify bottlenecks, review recovery priorities and make informed decisions about the resources and level of intervention required for each portfolio.
The Takeaway
Overdue invoices do not have to become permanent losses. With early identification, accurate account verification, professional customer engagement and a clear escalation process, businesses can improve their chances of recovering outstanding amounts.
Successful debt recovery is built on consistency, evidence and accountability. By managing each account through a structured process, organisations can protect cash flow, reduce avoidable disputes and maintain professional relationships with customers.
Need Support Recovering Outstanding Invoices?
Soluken Company Limited provides structured receivables-management and debt-recovery solutions designed to help organisations manage outstanding accounts and improve recovery performance.
Our support includes early-stage collections, business-to-business and consumer collections, payment restructuring, demand letters, field collections, skip and asset tracing, late-stage recovery, legal recovery support and recovery reporting. The approach is tailored to the account, the portfolio and the client’s recovery requirements.